Independent Mortgage Advisor in UK
Finding the right mortgage is one of the most important financial decisions you will ever make. With so many lenders, products, and criteria available, the home buying process can feel confusing and stressful. Working with an independent mortgage adviser in UK can make the journey smoother and more cost-effective. Whether you are a first-time buyer, a landlord building a buy-to-let investment, or a homeowner seeking a remortgage broker, independent advice helps you choose the right path with confidence.
Why Choose an Independent Mortgage Advisor in UK?
Benefits of Local Mortgage Advice
An independent mortgage adviser is not restricted to one bank or building society. Instead, they can search across the whole mortgage market to find the most suitable deal for your personal circumstances. This may include a fixed rate mortgage, a tracker mortgage, or an interest only mortgage depending on your goals.
Access to Qualified Advisers
Most brokers are CeMAP qualified mortgage advisers who provide professional guidance throughout the mortgage process. These financial professionals will prepare a personalised illustration showing how different interest rates, fees, and repayment types affect your monthly repayments and loan amount.
Support Beyond Mortgages
An adviser can also provide related financial advice. This might include life cover, arranging a life insurance policy, planning for equity release, or even discussing pension advice. This wider support ensures that your property purchase fits within your long-term financial planning.
How Independent Mortgage Advisors Help Landlords and Property Investors?
Buy-to-Let and Portfolio Mortgages
Landlords often face stricter criteria and larger mortgage deposits. An adviser can explain how affordability is assessed, what documents are required, and which lenders support buy-to-let investment. If you are a portfolio landlord with several properties, a broker can find lenders who specialise in these more complex cases.
SPV and Limited Company Mortgages
Many investors use Special Purpose Vehicle (SPV) limited companies to hold property for tax efficiency. Independent brokers know which lenders will accept SPVs, non-standard construction properties, or cases involving second charges.
Remortgaging and Capital Raising
Whether you want to release equity, secure a lower rate, or raise capital for further investment, a remortgage broker can help. Independent brokers understand how to manage refinancing, tax considerations such as self assessment, and legal costs including conveyancing services and Council Tax implications.
Comparing Mortgage Brokers and Bank Advisors
| Section | Details |
|---|---|
| Independent vs Tied Advisors |
|
| Cost of Mortgage Advice, Is It Worth It? | Most brokers offer a free initial consultation. Some may charge a fee, while others are paid commission by the lender. In practice, the money saved by securing the right deal usually outweighs any advisory costs. |
How to Choose the Best Independent Mortgage Adviser in UK
Key Qualities to Look For
- Regulated by the Financial Conduct Authority (FCA).
- Experience with both residential and buy-to-let investment mortgages.
- Clear explanation of fees.
- Flexible support through face-to-face appointments, telephone appointments, or online meetings.
Questions to Ask
- Which lenders do you work with?
- Do you advise on second charges or equity release?
- How do you charge for your services?
- What documents do I need for a decision in principle or mortgage in principle?
Types of Mortgage and Financial Products Available
Fixed Rate Mortgage vs Tracker Mortgage
A fixed rate mortgage locks in your rate, giving you certainty in your monthly repayments. A tracker mortgage follows the Bank of England interest rates, which may suit those willing to accept more flexibility.
Interest Only Mortgage
With an interest only mortgage, you only pay the interest each month, reducing costs in the short term but requiring a repayment plan at the end of the term.
Equity Release and Home Reversion Plans
Older homeowners may consider equity release, a home reversion plan, or other home reversion schemes to access money tied up in their property.
Offset Mortgages
Some lenders offer offset deals that link your mortgage with an offset savings account, helping reduce the amount of interest you pay.
Independent Advice for Home Buyers and Investors
Whether you are arranging a family deposit mortgage, considering equity release, or exploring second charge mortgages, an independent adviser can guide you. They will support you through the entire homebuying process, from the initial mortgage in principle to completion.
Some firms also offer refer a friend schemes, digital support for checking network usage and response times, and even online security steps such as human verification during applications.
Get Started
Working with an independent broker ensures you receive expert mortgage advice that is tailored to your needs. At NeedingAdvice.co.uk Ltd, our team of qualified advisers provide professional guidance for homebuyers, landlords, and property investors.
Speak with Damian
For clear, personalised mortgage advice, Damian can help you understand your options and choose a suitable route based on your circumstances.
Speak with Damian
Get clear, personalised mortgage advice from NeedingAdvice.co.uk Ltd. Damian can help you understand your options and choose a suitable mortgage route based on your circumstances.
Whether you are buying, remortgaging, investing in buy-to-let, or exploring specialist lending, you can get guidance tailored to your needs.
In short: an independent, whole-of-market mortgage broker can recommend products from across the lender market rather than from one lender or a restricted panel. Under FCA rules a firm must tell you in writing, before you apply, whether its advice is whole of market, from a limited panel, or from a single lender. Needing Advice is directly authorised and gives whole-of-market mortgage advice with no obligation to proceed.
Independent, Whole-of-Market Mortgage Advice
The words “independent”, “whole of market” and “tied” are not marketing language in UK mortgage advice. They are FCA-defined descriptions of the range a firm can advise on, and a firm has to disclose which one applies to it in the Initial Disclosure Document you are given before any recommendation is made. Knowing which you are dealing with is the single most useful question to ask a broker, because it determines whether the recommendation you receive was chosen from the whole market or from whatever the firm happens to have access to.
What the three descriptions actually mean
Whole of market means the firm can select from products across the lender market, including lenders that do not sell direct to the public. Panel or limited means the firm advises on products from a defined list of lenders, which may be short. Tied or single-lender means the adviser can only recommend one lender’s products, which is normally the case when you go into a branch or apply direct. A direct application is not automatically worse, but it is not advice across the market, and the lender has no duty to tell you that a different lender would have considered you.
Directly authorised versus appointed representative
A separate distinction sits underneath this. A directly authorised firm holds its own FCA permissions. An appointed representative operates under the permissions of a principal firm, which may restrict the products or lenders it can place business with. Both are legitimate and both are on the FCA Register, but the register entry tells you which one you are dealing with and what the firm is permitted to advise on. You can check any firm or adviser free of charge on the FCA Register before you share any personal or financial information.
Why Whole-of-Market Access Matters in Practice
For a straightforward case with employed income, a clean credit file and a standard property, the difference between whole-of-market and direct is often small. The difference becomes material the moment a case is not straightforward, because lender criteria diverge sharply at the edges and there is no public database that lets a consumer compare criteria across lenders.
Cases where the range of lenders available genuinely changes the outcome include: self-employed applicants with one year of accounts or with declining profits; contractors assessed on day rate rather than filed accounts; applicants with a default, CCJ or historic missed payments; income made up of bonus, commission, overtime, benefits or investment income, which lenders treat at widely differing percentages; non-standard construction such as concrete, timber frame, steel frame or ex-local authority high-rise; leases with a short unexpired term; properties above or adjacent to commercial premises; applicants near or past a lender’s maximum age at the end of term; and expatriate or foreign-national applicants. In each of these, a lender that will not consider the case is not evidence that no lender will.
What the advice process should include
A regulated mortgage recommendation should involve a documented affordability assessment, a discussion of your circumstances and plans for the term, a written illustration setting out the total cost including fees, and a suitability report explaining why the recommended product was chosen. You should also be told clearly how the firm is paid, whether that is a fee, commission from the lender, or both, and the amount before you commit.
What a Broker Costs and How to Compare
Some brokers charge the client a fee, some are paid by lender commission, and some use a combination. A fee-free broker is not being paid nothing, and a fee-charging broker is not necessarily more expensive once the product itself is accounted for. The comparison that matters is the total cost of the mortgage over the initial deal period, including any product fee, valuation fee, legal costs and broker fee, set against the alternative you would otherwise have taken. The written illustration is the document that lets you make that comparison, and you are entitled to one before you apply.
Frequently Asked Questions
What does whole of market mean for a mortgage broker?
Whole of market means the firm can advise on mortgage products from across the lender market rather than from a single lender or a restricted panel. The FCA requires firms to disclose their range in writing before giving a recommendation, so you should be told which applies before you apply.
Is an independent mortgage adviser better than going direct to a bank?
Neither is automatically better. A bank can only offer its own products and assesses you against its own criteria. An independent whole-of-market adviser can compare criteria across lenders, which matters most where income, credit history or the property itself is non-standard. For a simple case the outcome may be similar.
Do I have to pay for independent mortgage advice?
It depends on the firm. Some charge a client fee, some are paid by lender commission, and some both. Whichever applies, the firm must tell you how it is paid and how much before you commit, and set the cost out in your written illustration.
How do I check a mortgage adviser is genuine?
Search the firm or adviser on the FCA Register, which is free and public. It shows whether the firm is directly authorised or an appointed representative, what it is permitted to do, and its Firm Reference Number. Check this before sharing personal or financial details.
Does a mortgage adviser need to be local to me?
No. Regulated mortgage advice can be given by phone, video call or email anywhere in the UK, so an adviser does not need to be in your town. Local knowledge of property types and valuation issues can still be useful in some areas.
Can an independent broker access lenders I cannot apply to myself?
Yes. A number of UK lenders distribute only through intermediaries and do not accept applications direct from the public, so those products are not visible or available to a consumer applying on their own.
Related Guides
- UK mortgage requirements: what lenders ask for
- Getting an Agreement in Principle before you offer
- How many times your salary can you borrow?
- Specialist lending: non-standard cases
- What is a mortgage product fee?
Written and reviewed by Damian Youell CeMAP, senior mortgage and protection adviser. Needing Advice gives independent, whole-of-market mortgage advice with no obligation to proceed. Meet our team.
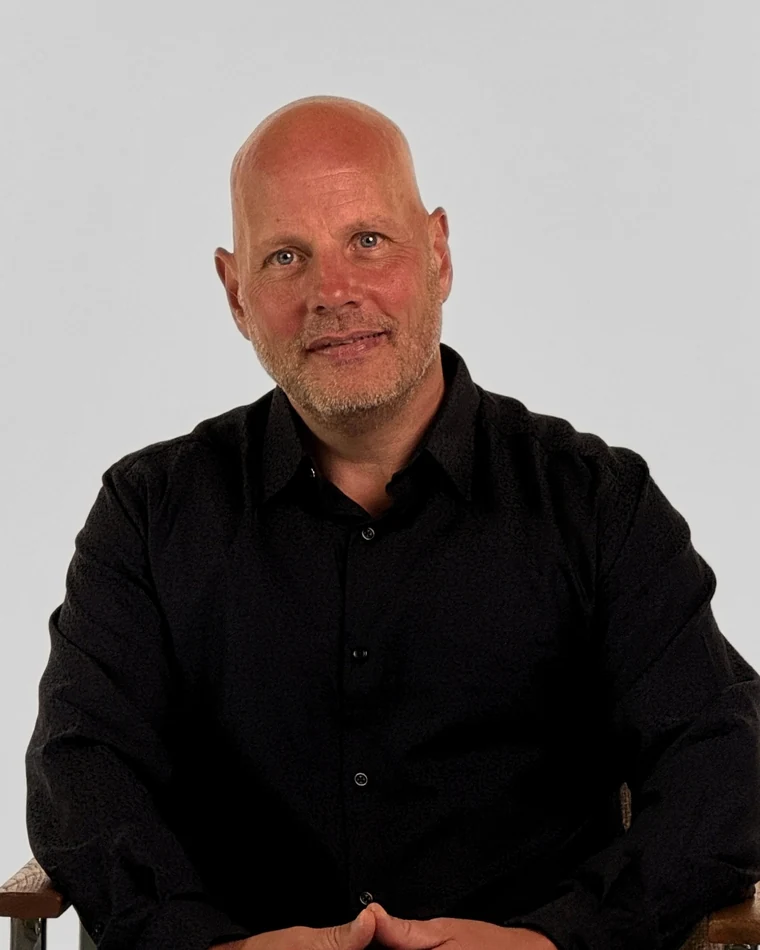
Damian Youell
Damian is the founder of NeedingAdvice.co.uk and the firm’s Senior Mortgage Broker. He specialises in helping clients across the UK with straightforward and complex mortgage cases, including self-employed applications, adverse credit, buy-to-let, remortgages and first-time buyer mortgages.
Alongside mortgage advice, Damian also supports business owners with protection planning, including Relevant Life Policies, Shareholder Protection and Keyperson Cover.
Read independent client feedback and verified reviews for Damian and the NeedingAdvice.co.uk team below.