Specialist Lending
Commercial mortgages, bridging finance and other cases the high street will not touch. Whole of market, FCA regulated, free first conversation.
When a standard mortgage does not fit
Specialist lending covers the cases mainstream lenders decline or price badly. That might be the property, the borrower, the timescale or the way the income is earned. It does not mean the case is a problem. It usually means it needs a lender who understands that type of case.
We work whole of market, including lenders who deal only through intermediaries and cannot be approached directly. If your case has been turned down elsewhere, or you have been told it is too complicated, it is worth a conversation before you assume the answer is no.
Commercial mortgages
Finance for premises you trade from or let out as a business, including shops, guest houses, care homes, kennels and holiday lets. Lenders assess the business as much as the property, so trading history, projections and experience all matter.
- How do you decide between a btl mortgage vs commercial loan when financing property in the UK?
- Commercial Mortgage Warehouse: A Practical Guide for UK Business Owners
- Commercial Mortgage Pre Approval: What UK Business Owners Need to Know
- Commercial Mortgage Eligibility: A Complete Guide for UK Business Owners
- Commercial Mortgage for Limited Company: The Complete UK Guide (2025)
- Commercial Mortgages for Start-Up Businesses in the UK: What You Need to Know
- Commercial Mortgage for a Shop: A Complete Guide for Business Owners
- Commercial Mortgage for Guest House
- Commercial Mortgage for First Time Landlords Explained
- Commercial Mortgage for Holiday Let: A Complete Guide
- Commercial Mortgage for Airbnb: Finance Options for Short-Term Lettings
- Commercial Mortgage for Care Homes: Expert Financing Solutions and Key Considerations
- Commercial Mortgage for Boarding Kennels
Bridging loans
Short term finance used to complete quickly, buy at auction, break a chain or fund a refurbishment before refinancing onto a longer term product. The exit route matters as much as the loan itself, and it is the first thing a lender will ask about.
- Refurb mortgage: what is it, and can you get one in the United Kingdom in 2026?
- Understanding Bridging Loan Repayment Terms in the UK
- Bridging Loan for House Purchase: A Guide for UK Property Investors
- How to Secure a Bridging Loan for Auction Property in the UK
- Bridging Loan for Property Flip: What You Need to Know
- How Long Do You Get to Pay Back a Bridging Loan?
- What is the Minimum Term for a Bridging Loan?
- What Are the Cons of a Bridging Loan?
- Do I Need a Salary for a Bridging Loan in the UK?
Other specialist cases we handle
Specialist lending is broader than commercial and bridging. These are the areas that come up most often.
- Adverse credit, including defaultsMissed payments on credit accounts, which can affect a borro... More, CCJs, missed payments and discharged bankruptcy
- Self employed mortgages, sole traders, contractors and company directors
- Non standard residency, including visa holders and applicants with overseas income
- Non standard property types, including flats above shops and unusual construction
- Buy to let and portfolio lending, including limited company structures
Guides on non-standard construction
Construction type is one of the most common reasons a mainstream lender says no. These guides cover the specific property types that narrow the lender list.
- Buy-to-Let Mortgage Renting to Serco
- Buying a Home with a CRL Structural Warranty in 2025
- Can You Get a Mortgage on a Cob House?
- Everything You Need to Know About the Laing Easiform Mortgage
- Getting a Mortgage without a NHBC Certificate
- Large Panel System Mortgage: A Simple Guide
- Livett-Cartwright Mortgages Explained
- Mortgage Kitchen Requirements
- Mortgage for House With 2 Kitchens
- Mortgage for Properties Near Mineshafts
- Mortgages and Unadopted Roads
- Open Deck Access Mortgages: A Flexible Way to Borrow Against Your Property
- Understanding Section 106 Mortgages: Eligibility, Process, and Lenders
- Understanding Tyneside Lease Mortgage
- Why Woolaway Construction Mortgages Are Hard to Secure
Guides on complex income
How your income is earned matters as much as how much you earn. These guides cover the income types lenders assess differently.
- Can I Get a Mortgage Using Latest Years Accounts?
- Can You Get a Mortgage on an Apprenticeship? Here’s What You Need to Know
- Can you get a mortgage with employment gap in 2026?
- Getting a Mortgage After Furlough in 2023
- How Does Working from Home Affect Your Mortgage? A Comprehensive Guide
- How to Get Approved for a Mortgage with Overtime Income?
- How to Secure a Mortgage with PhD Stipend?
- Mortgage With Crypto Income UK: Can You Get One?
- Mortgage for YouTuber (UK) in 2026
- Mortgage using spousal maintenance: Secure your dream home even after separation
- Stocks, Forex and Mortgages
- Taxi Driver Mortgages in the UK: A Complete Guide
- Turning RSUs into Keys
Guides on adverse credit
A mark on your credit file is rarely the end of the conversation. These guides cover the specific situations lenders will still consider.
Guides on family and deposits
Where a deposit comes from affects which lenders will accept it. These guides cover the less standard routes.
Common questions about specialist lending
What counts as specialist lending?
Anything a mainstream lender will not handle on standard terms. That includes commercial premises, bridging finance, adverse credit, complex income, unusual property types and non standard residencyThe borrower's residency status, such as whether they are a ... More.
Is specialist lending more expensive?
It can be, because the lender is taking on a case that needs more assessment. How much difference it makes depends entirely on the case, and comparing the whole market is what keeps the cost down.
I have been declined elsewhere. Is it worth trying again?
Usually yes. Lenders differ a great deal in what they will accept, and a decline from one says very little about what another would do. It is worth understanding why the decline happened first.
Do you charge for advice on specialist cases?
The first conversation is free and there is no obligation. Any fee is explained clearly and in writing before you commit to anything.
Speak to a specialist lending adviser
Damian Youell
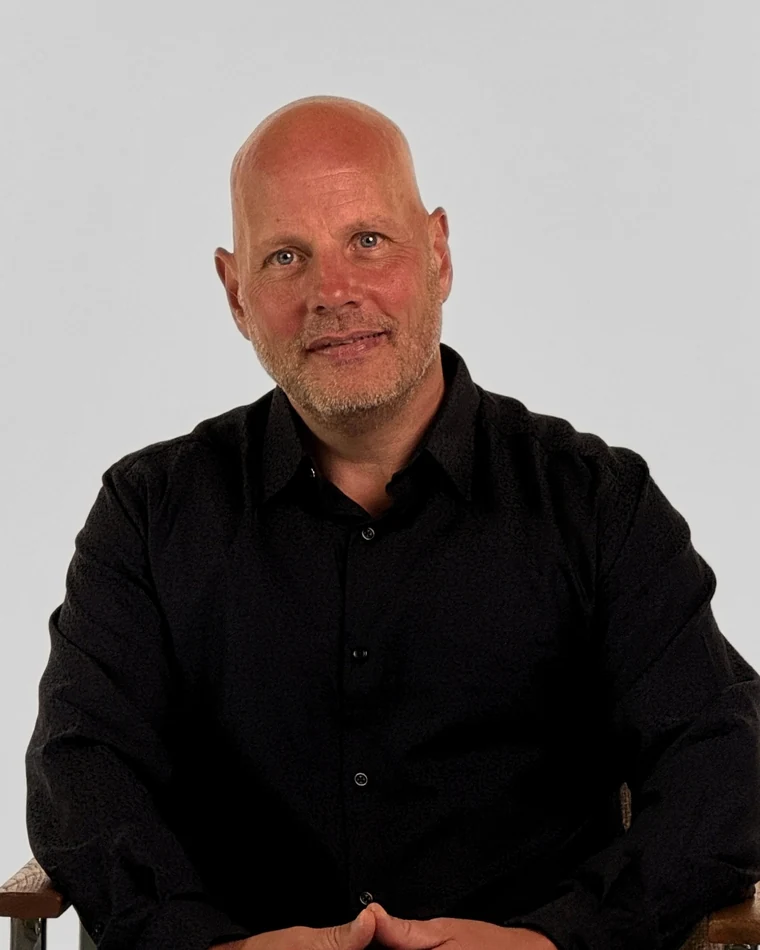
Damian is the founder of NeedingAdvice.co.uk and the firm’s Senior Mortgage Broker. He specialises in helping clients across the UK with straightforward and complex mortgage cases, including self-employed applications, adverse credit, buy-to-let, remortgages and first-time buyer mortgages.
Alongside mortgage advice, Damian also supports business owners with protection planning, including Relevant Life Policies, Shareholder Protection and Keyperson Cover.
Read independent client feedback and verified reviews for Damian and the NeedingAdvice.co.uk team below.
Your home may be repossessed if you do not keep up repayments on your mortgage. Some forms of commercial and bridging finance are not regulated by the Financial Conduct Authority. Needing Advice provides independent, FCA regulated mortgage advice. The guidance on this page is general information and not personal advice. Any recommendation is based on your own circumstances.